

· AFX Research
A Marital Home With a Mortgage in Forbearance, What to Check
The payments paused and the debt did not. How the arrears get resolved, what that puts on the record, and why a clean search is not evidence of a current loan.
Table of Contents
A couple separates while the mortgage is in forbearance. The payments stopped a year ago by agreement with the servicer, no default has been filed, and the search comes back without a notice of default or anything else alarming. Everyone reads that as the loan being in reasonable shape. It is not — forbearance exists precisely so that nothing gets filed, and the arrears sitting behind it are a real number that belongs in the settlement. This is a close relative of the timing problem in unreleased old mortgages, running the other direction.
What forbearance actually does
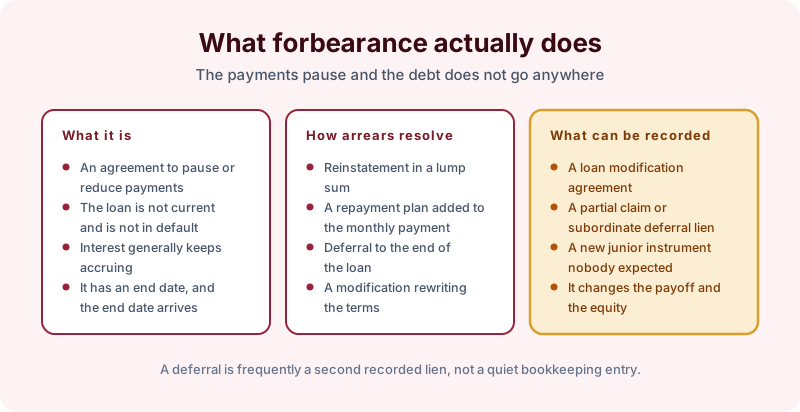
Forbearance is an agreement to pause or reduce payments for a period. The loan is neither current nor in default, interest generally continues to accrue, and the arrangement has an end date that eventually arrives.
How the arrears resolve is the part that matters to a property settlement. Reinstatement in a lump sum, which few people separating can manage. A repayment plan adding an amount to each monthly payment. Deferral of the arrears to the end of the loan. Or a modification rewriting the terms entirely.
Two of those four create recorded instruments. A loan modification agreement is frequently recorded. A deferral is often documented as a partial claim or subordinate lien, which means a second instrument appears against the property that nobody involved thinks of as a mortgage. Either changes the payoff, and therefore changes the equity being divided.
What the record shows
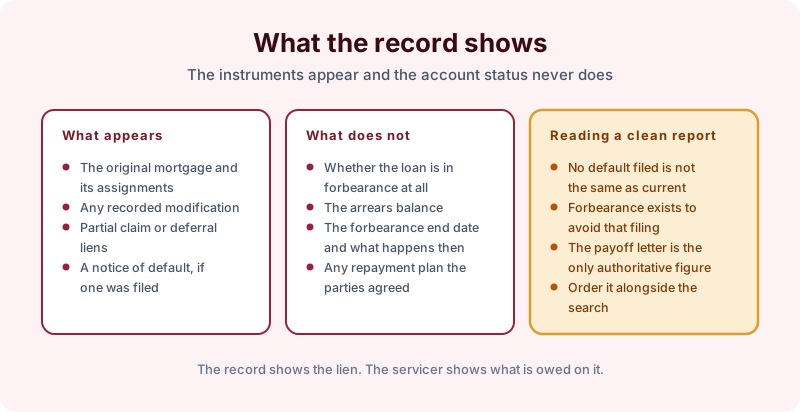
A search shows the original mortgage and its assignments, any recorded modification, any partial claim or deferral lien, and a notice of default where one was filed.
It shows nothing about the account. Whether the loan is in forbearance at all, the arrears balance, the end date, or any repayment plan the parties agreed are all servicing facts held by the servicer.
The absence of a recorded default is therefore not evidence of anything. Forbearance is designed to prevent exactly that filing, so the record stays quiet while the balance grows. The payoff letter is the only authoritative figure, and it should be ordered alongside the search rather than after it.
Why this breaks settlements specifically
Because the equity calculation uses a number that is wrong. A house valued at $410,000 against a mortgage balance everyone remembers as $280,000 looks like $130,000 of equity. If eighteen months of arrears, accrued interest and a deferred partial claim bring the real payoff to $312,000, the equity is $98,000 and somebody has agreed to a buyout priced on a figure that never existed.
There is also an assumability question. A spouse planning to keep the house generally cannot assume a loan that is not current, and may not qualify to refinance until the arrears are resolved, which is the practical obstacle in assuming the mortgage instead of refinancing.
Scoping the search
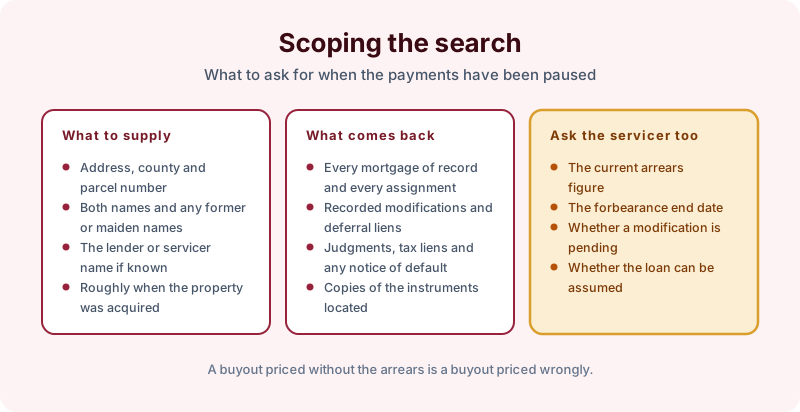
Supply the address, county and parcel number, both names with any former or maiden names, the lender or servicer name if known, and roughly when the property was acquired. What comes back is every mortgage of record with its assignments, any recorded modification or deferral lien, the judgments, tax liens and any notice of default, and copies of the instruments. Our process page sets out how that is done.
Ask the servicer separately for the arrears figure, the forbearance end date, whether a modification is pending, and whether the loan can be assumed. A records search reports what was recorded and indexed over the term searched, and an empty result does not establish that nothing is owed.
The takeaway
Forbearance keeps the record quiet while the balance moves, and the instruments it eventually produces are easy to misread as unrelated liens. Pair the search with a payoff letter before anybody agrees a buyout number. Start the order online, or send us the address and the names and we will tell you what a search of that scope would and would not cover before anything is ordered.